For decades, sending money internationally meant surrendering 5–10% of your transfer to banks and remittance services, waiting 3–5 business days, and navigating a chain of correspondent banks that added cost at every step. Cryptocurrency is fundamentally disrupting this model — and millions of people around the world are taking notice.
The Problem With Traditional International Transfers
When you send money through a traditional bank wire or remittance service, your money passes through multiple intermediaries before reaching its destination. Each one takes a cut. A $1,000 transfer from the UK to India through a major bank can cost $25–$50 in fees, plus an unfavourable exchange rate spread that quietly takes another 2–3%. By the time the money arrives — often 3 to 5 business days later — the recipient may receive significantly less than expected.
For the 281 million migrants worldwide who regularly send money home to their families, these costs add up to billions of dollars lost every year to financial intermediaries.
How Crypto Cross-Border Transfers Work
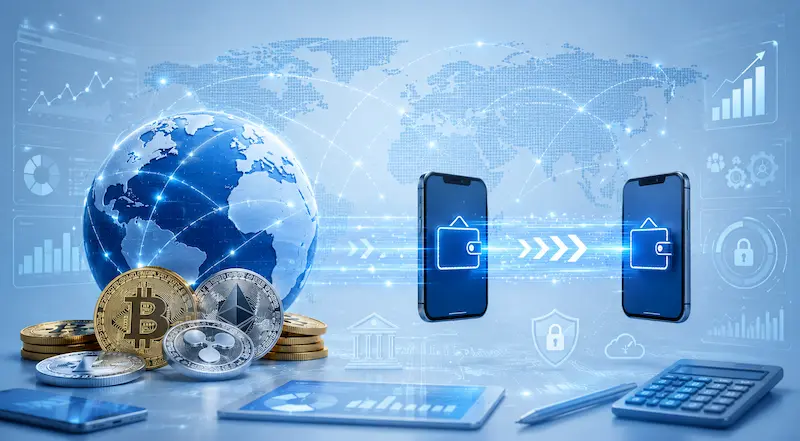
Cryptocurrency transfers work differently at a fundamental level. Instead of routing money through correspondent banks, a crypto transfer moves value directly between two digital wallets — anywhere in the world — on a shared blockchain network. There are no intermediaries, no banking hours, and no geographic restrictions.
The process is straightforward: the sender purchases cryptocurrency — Bitcoin, USDT, or XRP — on an exchange in their country. They send it directly to the recipient's wallet address. The recipient receives the crypto within minutes and can either hold it, convert it to local currency on a local exchange, or spend it directly where crypto is accepted. The entire process can cost less than $1 in network fees, regardless of the amount being sent.
Which Cryptocurrencies Are Best for Remittances?
Not all cryptocurrencies are equally suited for cross-border payments. Three stand out for practical remittance use:
Bitcoin (BTC) is the most widely recognised and accepted cryptocurrency globally. Its main limitation for remittances is transaction speed — Bitcoin transfers can take 10–60 minutes to confirm — and fees can spike during periods of high network demand. It is better suited for larger, less time-sensitive transfers.
USDT (Tether) is a stablecoin pegged to the US Dollar, making it ideal for remittances because the recipient knows exactly what value they will receive — there is no price volatility between sending and receiving. USDT on the Tron network is particularly popular for international transfers due to extremely low fees, often under $1.
XRP (Ripple) is specifically designed for cross-border payments, settling transactions in 3–5 seconds with fees of fractions of a cent. Several financial institutions and payment providers use the XRP network infrastructure for international settlement.
Real-World Cost Comparison
To put the savings in concrete terms, consider sending $500 from the United States to the Philippines — one of the world's largest remittance corridors.
A traditional wire transfer through a major bank typically costs $25–$45 in fees plus an exchange rate margin of 2–3%, meaning the recipient might receive the equivalent of $440–$460. Sending $500 worth of USDT directly to a Philippine recipient costs less than $1 in network fees. The recipient receives the equivalent of $499 and can convert to Philippine Pesos on a local exchange within minutes.
The Currency Conversion Advantage
One underappreciated benefit of crypto remittances is the ability to use real mid-market exchange rates rather than the heavily marked-up rates banks offer. When converting currencies for an international transfer, traditional banks typically add a 2–4% spread on top of the actual market rate — pure profit for the bank and pure loss for the sender.
With crypto, senders and recipients can access the actual market exchange rate through cryptocurrency exchanges. If you want to check live mid-market exchange rates before deciding how to send money, FloatForex's live currency converter lets you compare rates in real time.
Challenges and Considerations
Volatility remains the biggest concern for non-stablecoin transfers. If you send Bitcoin and the price drops 5% during the transfer window, the recipient receives less value than intended. Stablecoins like USDT largely solve this problem.
Regulatory uncertainty varies significantly by country. Some countries have embraced crypto remittances openly — El Salvador made Bitcoin legal tender specifically to facilitate cheaper remittances. Others have imposed restrictions on crypto exchanges and conversions. Always check the regulatory status in both the sending and receiving country.
Recipient accessibility requires that the recipient has a crypto wallet and access to an exchange where they can convert crypto to local currency. In some regions, this infrastructure is still developing, though it is improving rapidly.
Scams and errors are a real risk. Crypto transactions are irreversible — if you send to the wrong wallet address, the funds cannot be recovered. Always double-check wallet addresses before confirming any transfer.
The Bigger Picture
Crypto cross-border payments represent more than just a cheaper way to send money — they represent a fundamental shift in financial access. For the 1.4 billion adults worldwide who remain unbanked, cryptocurrency offers a path to participate in the global economy without requiring a traditional bank account. All that is needed is a smartphone and an internet connection.
As blockchain infrastructure matures, regulatory frameworks clarify, and stablecoin adoption grows, crypto is increasingly positioned not as a fringe alternative to traditional remittances but as the mainstream default — particularly for corridors where traditional banking is expensive, slow, or simply unavailable.
The question for many people is no longer whether crypto can be used for international transfers. It is how quickly the rest of the world catches up to those already using it.