Inflation does not announce itself loudly. It works quietly — reducing the purchasing power of every dollar, pound, or euro you hold in savings, gradually and relentlessly, year after year.
At 3 percent annual inflation, $100,000 in a savings account becomes the equivalent of $74,000 in real purchasing power after ten years — even if the nominal balance never changes. At 6 percent inflation, that same $100,000 becomes the equivalent of just $55,000 in real terms over the same period.
This is not a theoretical risk. It is happening right now, in most major economies, to most people who are not actively doing something about it.
The good news is that protecting money from inflation is not complicated. It does not require sophisticated investment knowledge or large capital. It requires understanding which assets hold their value when paper money loses it — and allocating accordingly.
Here are the five best inflation hedges that have a proven track record across multiple inflationary cycles — what each one does, why it works, and how to use it practically.
Inflation Hedge 1: Gold — The 5,000-Year Store of Value
Gold is the oldest and most tested inflation hedge in human history. Its effectiveness is not based on sentiment or tradition — it is based on a fundamental characteristic that no paper currency shares: gold cannot be printed.
When governments and central banks respond to economic crises by creating more money — as they did on an unprecedented scale during the 2020 pandemic — the supply of paper currency increases while the supply of gold grows by only 1 to 2 percent per year through mining. More money chasing the same amount of goods and assets pushes prices up. Gold, with its constrained supply, holds its purchasing power while the purchasing power of paper money falls.
The historical evidence is clear. In every major inflationary period of the past century — the 1970s stagflation, the post-2008 quantitative easing era, the 2021-2023 inflation surge — gold significantly outperformed cash and most fixed-income assets in real terms.
Gold crossed $3,000 per ounce in 2024 and has continued rising into 2026, driven by a combination of persistent inflation, central bank buying at record levels, and geopolitical uncertainty creating safe haven demand. The structural case for gold as an inflation hedge has rarely been stronger.
How to use it: Most financial advisors suggest allocating 5 to 15 percent of a portfolio to gold as an inflation hedge — enough to provide meaningful protection without overconcentration in a single asset.
Track live XAU/USD gold prices and historical charts to monitor your gold allocation in real time at floatforex.com/gold-charts
Inflation Hedge 2: Real Assets — Property and Commodities
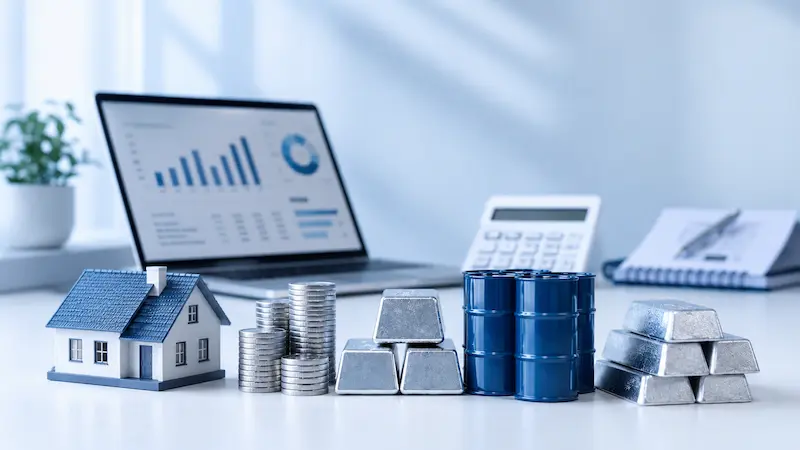
Real assets — physical things with intrinsic value — have historically maintained purchasing power during inflationary periods because their prices tend to rise alongside the general price level.
Real estate is the most widely held real asset. Property values and rental income typically rise with inflation, meaning real estate investors are partially insulated from purchasing power erosion. The challenge is that real estate is capital-intensive, illiquid, and heavily affected by interest rate changes — rising rates increase mortgage costs and can suppress property values even during inflationary periods, as seen in 2022 and 2023.
Commodities — oil, natural gas, agricultural products, industrial metals — are even more directly connected to inflation because they are inputs to the production of almost everything. When commodity prices rise, the cost of producing goods rises, which feeds directly into consumer price inflation. Holding commodity exposure — through ETFs, futures, or commodity-producing company shares — gives you participation in the inflation cycle rather than exposure to it.
Silver, often overlooked in favour of gold, is both a precious metal and an industrial commodity — giving it dual inflation protection characteristics. The Gold/Silver ratio, currently at historically elevated levels, suggests silver may be undervalued relative to gold as an inflation hedge at present valuations.
How to use it: Real estate investment trusts (REITs) provide real estate exposure without direct property ownership. Broad commodity ETFs provide diversified commodity exposure in a single liquid instrument.
Inflation Hedge 3: Treasury Inflation-Protected Securities (TIPS)
TIPS are government bonds specifically designed to protect against inflation. Unlike conventional bonds — which pay a fixed interest rate on a fixed principal that loses real value as inflation rises — TIPS adjust their principal value in line with the Consumer Price Index.
When inflation rises, the principal of a TIPS bond increases automatically. Interest payments, calculated as a percentage of the adjusted principal, also rise. When inflation falls, the principal adjusts downward — but at maturity, investors receive at minimum the original principal, providing a floor against deflation.
TIPS are issued by the US Treasury and carry the same credit quality as conventional US government bonds — making them one of the few inflation hedges that combines purchasing power protection with minimal credit risk.
The limitation of TIPS is that their real yield — the return above inflation — can be negative when demand is high and conventional bond yields are low. During periods when real yields are negative, TIPS protect purchasing power but do not generate meaningful real returns. They are a defensive instrument rather than a growth instrument.
How to use it: TIPS are most appropriate for the fixed-income portion of a portfolio — as a replacement for conventional bonds during periods of elevated inflation risk rather than as an addition to existing allocations.
Inflation Hedge 4: Currency Diversification
One of the most underutilised inflation hedges available to individuals is currency diversification — holding savings or investments denominated in currencies that are likely to hold their value better than your home currency during inflationary periods.
Not all currencies are equally affected by inflation. Currencies backed by strong central bank credibility, sound fiscal policy, and commodity export revenues tend to outperform high-inflation currencies significantly over time. The Swiss Franc has historically been one of the strongest stores of value among major currencies — the Swiss National Bank's focus on price stability and Switzerland's current account surplus have made the CHF a long-term outperformer against higher-inflation currencies.
For individuals in countries experiencing elevated inflation — whether in emerging markets like Turkey and Argentina or in developed markets during inflationary periods — holding a portion of savings in USD, CHF, or other stable currencies provides meaningful purchasing power protection that domestic savings accounts cannot offer.
The rise of stablecoins — dollar-pegged digital currencies — has made currency diversification more accessible than ever. Dollar-pegged USDT and USDC allow individuals in any country to hold dollar-denominated savings without a US bank account, directly accessible from a smartphone.
How to use it: Monitor live exchange rates across major currency pairs to identify currency strength and diversification opportunities. Track USD/CHF, USD/JPY and other major pairs in real time at floatforex.com/currencies
Understanding how central bank policies affect currency values is covered in detail in the FloatForex guide at floatforex.com/blog/how-central-banks-move-currency-markets
Inflation Hedge 5: Equities — Specifically the Right Kind
Equities — shares in companies — have a more complicated relationship with inflation than the other hedges on this list. Stocks are not a reliable short-term inflation hedge. During periods of rising inflation combined with rising interest rates — as in 2022 — stocks often fall significantly as higher rates reduce the present value of future earnings and increase borrowing costs.
Over longer periods however — five years and beyond — equities have historically outpaced inflation significantly. Companies can raise prices when their input costs rise, passing inflation through to consumers and maintaining real profit margins. This pricing power is the mechanism by which equities provide long-term inflation protection.
The key distinction is between different types of equities. Companies with strong pricing power — those selling products or services that consumers and businesses cannot easily reduce spending on — maintain real profitability during inflationary periods better than companies selling discretionary products in competitive markets.
Commodity-producing companies — mining firms, energy producers, agricultural companies — benefit directly from rising commodity prices during inflationary periods and represent a hybrid between equity and commodity exposure.
How to use it: Focus equity allocations during inflationary periods toward companies with strong pricing power and commodity producers rather than growth companies whose valuations depend on low discount rates.
The Compound Interest Factor — Why Timing Your Inflation Hedge Matters
One aspect of inflation protection that is rarely discussed is the interaction between inflation hedges and compound growth. The returns generated by inflation hedges do not just protect purchasing power — when reinvested, they compound over time into significantly larger real wealth preservation.
Consider two scenarios for $50,000 over 20 years at 4 percent annual inflation:
- No hedge — cash savings: Real purchasing power falls to approximately $22,800 — less than half the original value.
- With inflation hedge returning 6 percent annually: The nominal value grows to approximately $160,000 while real purchasing power grows to approximately $72,000 — more than three times the unhedged outcome.
Model the compound growth impact of different inflation hedge return scenarios using the free compound interest calculator at floatforex.com/compound-calculator — entering your current savings, expected return, and time horizon to see exactly how compounding interacts with inflation protection over your specific timeframe.
Building Your Personal Inflation Protection Strategy
The most effective approach to inflation protection is not choosing one hedge — it is combining several in proportions appropriate to your situation, risk tolerance, and time horizon.
A practical starting framework for a moderate risk profile:
- Gold — 10 percent: Core inflation and crisis protection. Track live prices at floatforex.com/gold-charts
- Real assets (REITs or commodity ETFs) — 15 percent: Broad real asset exposure with liquidity.
- TIPS — 20 percent: Replace conventional bonds with inflation-linked equivalents.
- Currency diversification — 10 percent: Hold a portion of liquid savings in stable foreign currencies or dollar-pegged stablecoins.
- Equities with pricing power — 45 percent: Long-term real growth engine with inflation pass-through capability.
The specific percentages matter less than the principle: each allocation should serve a distinct role in protecting purchasing power under different inflation scenarios, and the combination should be more resilient than any single hedge alone.
The Bottom Line
Inflation is not a risk that appears and disappears. It is a permanent feature of modern monetary economies — sometimes mild, sometimes severe, but always present and always eroding the purchasing power of uninvested cash over time.
The five hedges above — gold, real assets, TIPS, currency diversification, and the right kind of equities — represent a toolkit that has been tested across multiple inflationary cycles and multiple decades. None of them is perfect. All of them are meaningfully better than doing nothing.
Understanding them, combining them thoughtfully, and monitoring the live market data that tells you how inflation and asset prices are interacting right now is what separates investors who preserve wealth through inflationary periods from those who discover too late how much they lost.
For live gold prices, currency rates, and financial calculators to support your inflation protection strategy, visit FloatForex.com